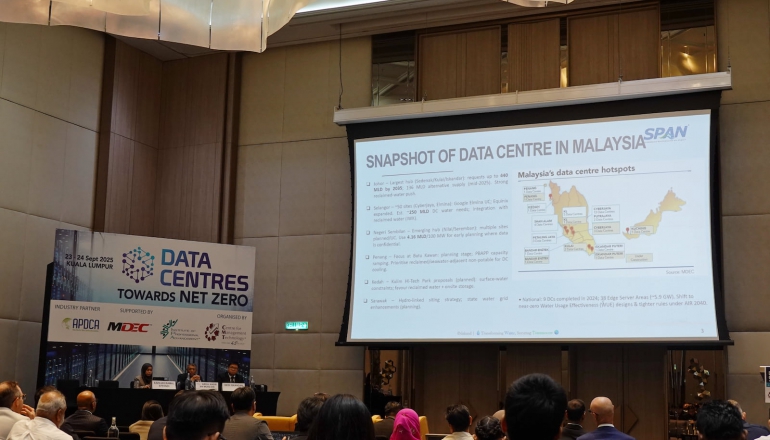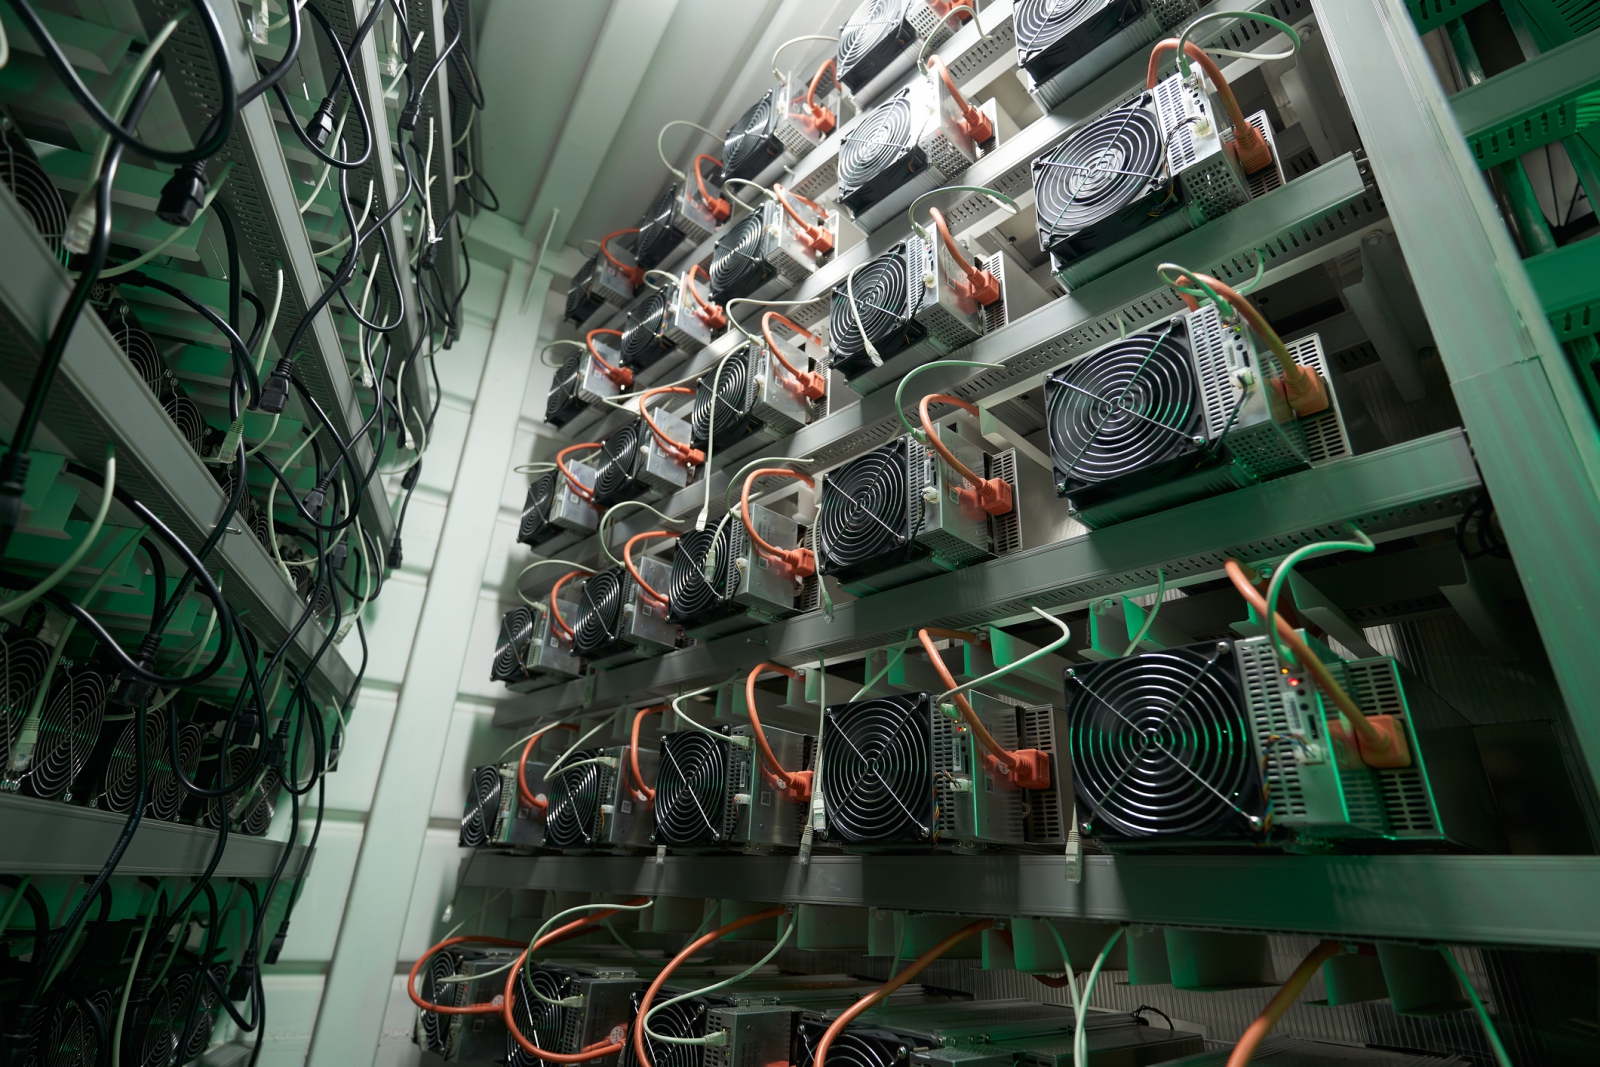
The rapid growth of large data centers in ASEAN is fueling strong demand for low-carbon energy. (Photo: iStock)
Global digitalization is driving a surge in demand for AI data centers, which have become major sources of energy consumption and carbon emissions. With the global energy transition accelerating and companies under mounting pressure to meet net-zero goals, decarbonizing data centers has become an urgent task. This series, “Race to green data centers,” explores how businesses, technologies, and markets are shaping solutions and charting the path toward sustainable digital infrastructure.
In Southeast Asia, where coal remains the dominant source of power generation, the rapid growth of data centers is intensifying pressure on electricity supply. As a result, access to low-carbon energy has become a critical factor in site development. From an energy perspective, RECCESSARY analyzes the advantages and challenges of three ASEAN countries leading in data center growth and features insights from regional power experts on the trajectory of the sector.
ASEAN data center growth divided into three phases as AI drives major shifts
Construction costs and electricity prices in Southeast Asia are generally lower than the global average. Combined with the region’s fast-growing digital economy and technology sector, this has made Southeast Asia a hotspot for data center development. According to a report by US consulting firm BCG, the region’s growth can be divided into three phases, with the third phase beginning in 2024.
Phase I, from 2014 to 2018, marked Singapore’s rise as a regional hub for data centers. Additional capacity during this period was supported by existing Asia Pacific hubs such as Australia, Hong Kong, and Japan, with overall capacity rising from 0.36 GW to 0.79 GW.
Phase II, from 2019 to 2023, saw data center capacity in Southeast Asia more than double to 1.69 GW within five years. During this period, Singapore slowed development due to constraints on energy and water resources, pushing demand to Johor in Malaysia and Batam in Indonesia. This shift laid the foundation for Singapore-Johor-Batam (SJB) corridor and set the stage for broader regional expansion.